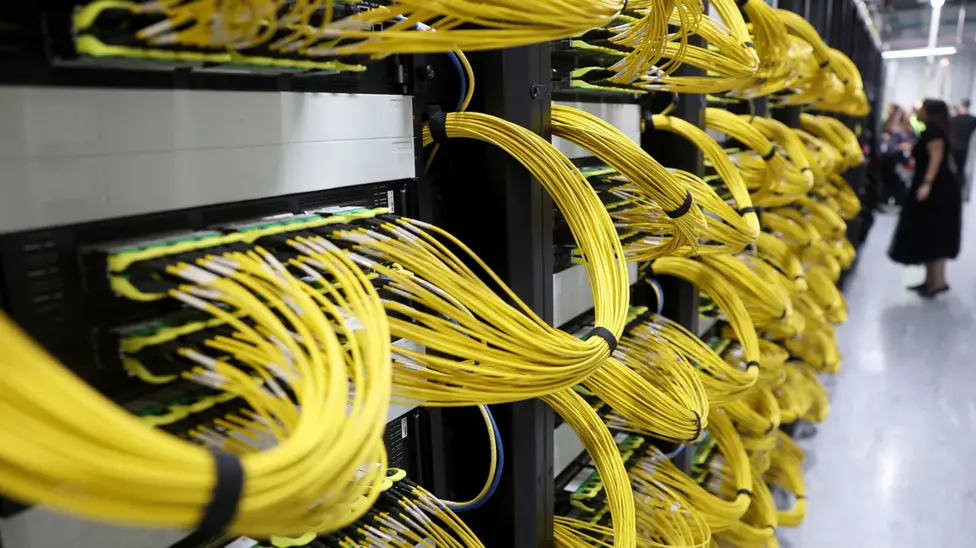
Neocloud companies often secure funding through long-term lease agreements with major tech clients needing rapid access to computational resources. As explained by analyst Cory Johnson from “The Quiet Period” IPO research firm, these businesses can leverage those contracts, along with the AI chips they acquire, as collateral to obtain loans. This reliance on debt is prevalent among neocloud firms, necessitating upfront payments for hardware.
Take, for instance, CoreWeave, the industry leader, which, despite being significantly smaller than some major tech firms it serves, has managed to accumulate a staggering $35.1 billion (£26.3 billion) in debt. Johnson notes that lenders may sometimes evaluate the creditworthiness of CoreWeave’s clients, such as Microsoft and Meta, more than the company itself.
However, some investors are growing uneasy, as evidenced by CoreWeave’s stock, which has plummeted by 25% in the past month. Other neocloud firms, including Nebius, IREN, and Applied Digital, have experienced similar declines. Debt investors are also reacting by demanding higher returns from various companies within the sector.
CoreWeave’s CEO, Mike Intrator, has expressed that the market is behaving “irrationally” and remains confident in their business model. Significant companies are lining up for CoreWeave’s infrastructure and AI services.
Interestingly, many neocloud firms have roots in the volatile crypto mining sector, which shares similar physical infrastructure with AI development. CoreWeave, for example, was established in 2017 with a focus on mining Ethereum, while IREN, Core Scientific, and Applied Digital also originated from crypto mining.
As AI surged in popularity in 2022, particularly with the launch of OpenAI’s ChatGPT, these companies found themselves well-positioned for growth. Meanwhile, Nebius, formerly Yandex NV, has transitioned from being part of Russia’s Google to operating independently since its name change in 2024.
The fate of neocloud firms now largely relies on the performance of major AI developers and hyperscalers, who are often their key clients. Melissa Otto, head of Visible Alpha Research at S&P Global, highlighted the significant spending influx into the system, describing it as an “arms race” that has benefited neoclouds. However, this model also carries “greater financial risk” amid potential changes in spending from their Big Tech customers.
Recent forecasts from Microsoft and Google indicated lower-than-expected AI spending, causing shares in several neocloud firms to decline sharply. The upcoming public offerings of Anthropic and OpenAI also loom large over the sector. If the AI market experiences a bubble burst, neocloud firms could suffer significant collateral damage, according to Bradley Tusk of Tusk Ventures.
Moreover, the ability of these companies to continue borrowing is being tested as interest rates rise. Elon Musk recently mentioned on social media that this situation could lead to significant consolidation among neoclouds, with over 200 potentially facing severe challenges, particularly the smaller firms.
Currently, analysts at Yorkville Ives note that the demand for computing power still surpasses supply, indicating that neoclouds are filling a crucial gap that larger data center companies cannot address. Nonetheless, the recent instability in the neocloud sector raises concerns. For instance, Microsoft recently terminated a deal with a British neocloud company, Nscale, due to power supply issues expected to persist until 2030. Likewise, Australia’s Firmus has postponed its plans for a public offering.
These events come amid growing public resistance to data centers and skepticism regarding the actual value AI can contribute to workforce productivity. Johnson cautions, “There’s reason to worry.”